|
By:
Stijn Van Nieuwerburgh
- Earle W. Kazis and Benjamin Schore Professor of Real Estate, Finance Division
- Co-Director, Paul Milstein Center for Real Estate
October 6, 2026
For a data center investor, a signed lease with a major technology company is a powerful selling point. The tenant has deep pockets, demand for computing capacity is growing, and access to power limits competing supply. Put those features together, and a new campus can look like an unusually attractive real estate investment.
But the lease is only the beginning of the underwriting. Somewhere behind the rent check, customers must pay enough for AI services to support the buildings, electricity, and chips being assembled on an extraordinary scale. How much revenue does that require? And what happens to the landlord and lender if the answer proves harder to achieve than expected?
In my recent paper, Financing the AI Buildout, I examine the investment pipeline and the financing arrangements supporting it. For real estate practitioners, the central finding is that the economics of the tenant's business, the useful life of the infrastructure, and the terms of the financing need to be evaluated together.
Start with the scale. A representative 200-megawatt AI campus costs approximately $8.2 billion, including computing equipment. Roughly one-third pays for the facility and associated power infrastructure; two-thirds pays for IT equipment. Applying those costs to a scenario for the U.S. development pipeline produces nearly $9 trillion of investment during 2025–2032, with about 188 gigawatts of additional capacity operational by 2032. This scenario already allows for substantial cancellations and downsizing relative to the announced pipeline and assumes no further additions to that pipeline. It also does not factor in the cost of IT refresh after the initial vintage of IT capital has reached the end of its useful life. Thus, while enormous, the $9 trillion buildout estimate may prove to be conservative.
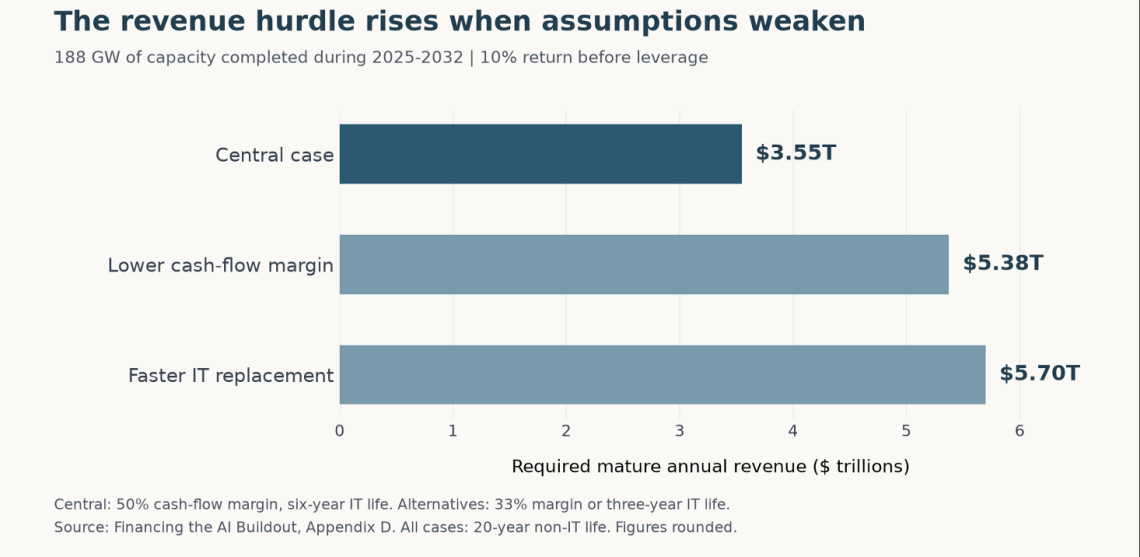
The revenue needed to support that investment is equally striking. My paper asks what the completed capacity must earn to recover its cost and provide investors with a return. The central calculation assumes a 10 percent annual return before leverage, a 50 percent operating cash-flow margin, a six-year economic life for IT equipment, and a 20-year life for the remaining assets. It also compensates investors for capital committed during construction.
The result is approximately $3.55 trillion in annual revenue by 2032, once the capacity is operating and mature. That is equivalent to 8.8 percent of projected U.S. GDP in 2032. Greg Ip's recent Wall Street Journal article puts that roughly 9 percent figure at the center of the discussion. It is a useful way to convey the magnitude of the commercial challenge.
The interpretation matters. This is a required revenue calculation, not a prediction of what customers will spend. Nor is it a calculation of data center rents: it covers the combined investment in facilities, power infrastructure, and computing equipment. Expressing revenue as a share of GDP provides a sense of scale; it does not establish that an equivalent share of domestic final spending must go to AI.
For practitioners, the more revealing comparison may be with the price and utilization of computing capacity. Using the paper's benchmark hardware configuration, the central revenue requirement works out to about $5.10 per installed GPU-hour if every hour is sold. At 80 percent utilization, the required price rises to roughly $6.40 per billed hour; at 70 percent, it reaches about $7.30. These are prices for access to the specialized processors that run AI workloads.
The paper finds that these requirements are broadly comparable to observed frontier-compute rental prices in late August 2026. That makes the economics conceivable. The harder question is whether providers can maintain those prices while filling an enormous amount of new capacity. Today's shortage can support attractive pricing. It cannot establish what pricing will look like after today's construction pipeline opens.
This is a familiar real estate problem with an unfamiliar underlying business. A market can have strong demand growth and still deliver disappointing investment returns if supply grows faster, rent growth is weaker than expected, or operating costs absorb too much of the revenue. AI adoption can succeed while particular campuses struggle to meet their underwriting.
Two assumptions deserve particular attention. First, the operating margin. If only one-third of revenue becomes operating cash flow, rather than one-half, the same completed capacity needs approximately $5.38 trillion in annual revenue to support a 10 percent return. While a 50% margin is close to the average margin of the hyperscalers today, it is arguable too high for other companies in the AI ecosystem such as the neoclouds, and there may be margin compression for the hyperscalers in the future. Investors should ask how much room the tenants have to absorb competition, power costs, and other expenses before their infrastructure commitments become burdensome.
Second, equipment life. If the IT equipment remains economically useful for three years rather than six, the central revenue requirement rises to approximately $5.7 trillion annually. The distinction between a chip that still works and a chip that remains competitive is crucial. Faster replacement consumes cash even when the buildings remain fully usable.
|